
Government Actuary’s Department freehold risk-premium needs a radical update
Property tribunal accepted data of 706 Allsop residential auction sales between September 2019 and February 2023 showing the fall in freehold values
The Government’s consultation on the valuation rates for leasehold enfranchisement presents an opportunity to do something which should have been obvious from the beginning: look at what investors actually pay for freeholds and ground rents.
The consultation closes now closes on 21 October, having been extended for another four weeks from 23 September, and will determine the capitalisation and deferment rates to be prescribed under the Leasehold and Freehold Reform Act 2024 (LAFRA).
These rates will be central to the new statutory valuation system for lease extensions and collective enfranchisement. And, of course, conversion of existing blocks of flats to commonhold.
The Government says the objective is to align these rates to reflect the market value of the properties in question. That makes the secondary market rather important.
There is a real market in residential freeholds and ground rents. Investors buy these assets, sell them and price the income they produce together with the prospect of eventually obtaining vacant possession. Their transactions therefore provide direct evidence of the return required to own the asset.
Government should use that evidence as a reality check for the statutory rates.
For capitalisation, the evidence is particularly accessible.
Ground-rent investments are bought and sold regularly, and the prices paid can be translated into yields. There is already evidence suggesting that the implied capitalisation rate derived from these yields are considerably higher than the rates that have traditionally been used in enfranchisement valuations.
For example, an analysis of 706 Allsop residential auction sales between September 2019 and February 2023 was put before the First-Tier Tribunal in this case:
The tribunal regarded the auction transactions as useful evidence of arm’s-length market sales and preferred the market-based analysis to the conventional figures advanced by the freeholder’s valuer.
The analysis has subsequently been cited as indicating an average capitalisation rate of around 9%. This is before any ground rent cap that may be introduced via the Commonhold and Leasehold Reform Bill or the commencement of LAFRA’s 0.1% cap on the value of ground rents for lease extensions and enfranchisement claims.
Of course, that does not mean 9% should simply be inserted into the statutory formula.
The transactions need to be examined properly and compared with the interests being valued. However, it would be remarkable if such a substantial body of actual transactions were not used to test whether the statutory assumptions correspond with investor behaviour.
The same exercise should be undertaken for deferment.
Freeholds are traded with reversions at very different points in the future. A transaction involving a freehold where the leases have 50 years to run tells us something about the return required to wait for the reversion. So does one where the leases have 80 or 120 years remaining.
Properly analysed, those transactions could provide an important market cross-check against the prescribed deferment rate.
There may be reasons why transaction yields cannot be transferred directly into the statutory methodology. Individual freeholds differ. Investors price particular risks differently. Transaction costs and liquidity matter.
But those are reasons to analyse the evidence, not reasons to disregard it.
If the Government wants market value, it should first establish what the market is saying. That is particularly important because the Government is now revisiting the valuation assumptions that have governed leasehold enfranchisement for almost 20 years.
The market is turning against these ground rent funds:
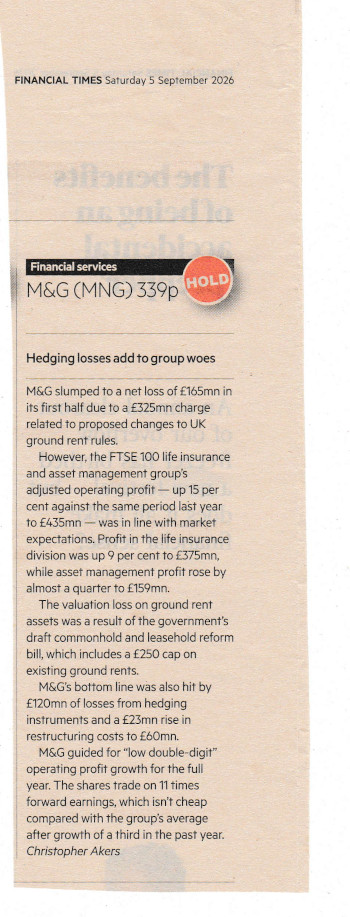
It is the same story with the Ground Rent Income Fund, explained here:
What has changed since Sportelli?
The Sportelli decision in 2007 established deferment rates of 5% for flats and 4.75% for houses.
The Government Actuary’s Department has subsequently done substantial work on investment yields and property-price growth, and that work is an important part of the present exercise. But deferment is not determined by those factors alone.
The Sportelli formulae has three principal components: the risk-free rate, the expected growth in property values and the risk premium for holding the freehold rather than the risk-free investment.
The risk premium is therefore not some minor adjustment at the margins of the calculation. It is one of the fundamental inputs into the final deferment rate.
Indeed, in the Sportelli analysis it accounted for a substantial part of the difference between the risk-free rate and the eventual deferment rate. That makes the treatment of the risk premium at least as important to the final answer as the other major assumptions being revisited by the Government Actuary’s Department.
If the Government is going to retain the Sportelli conceptual framework, it needs to examine the whole framework, including the risk premium. You cannot update a formula by looking at only some of its components.
The right question is not whether every risk faced by a freeholder today was absent in 2007. Many plainly were not: collective enfranchisement existed; lease extensions existed; Right To Manage existed and disputes with leaseholders existed. Those risks were therefore capable of being reflected in the original assessment.
The relevant question is what has changed since then.
One important change is building safety. The post-Grenfell regime has created responsibilities and potential liabilities for building owners that did not exist in their current form when Sportelli was decided.
In qualifying cases, leaseholders are protected from unsafe cladding remediation costs, leaving the building owner responsible for paying or securing the necessary remediation. The legislation has also created mechanisms including remediation orders and remediation contribution orders. These change the risk attached to the freehold.
The other significant change is the cost of dealing with statutory rights which themselves are not new. The right to manage is a good example. RTM existed in 2007, but the cost regime has changed with the commencement of the relevant provisions of LAFRA in 2025.
Under the new arrangements, leaseholders exercising RTM rights will generally no longer have to meet the freeholder’s process costs. The freeholder therefore bears costs that could previously be recovered from the other side.
The same principle will be applied to lease extensions and collective enfranchisement when the relevant LAFRA provisions are fully brought into force.
Historically, the leaseholder exercising the statutory right has generally had to pay the freeholder’s reasonable costs of dealing with the claim, as well as their own professional costs. Under LAFRA, the general rule will instead be that each side bears its own non-litigation process costs, subject to limited exceptions.
This is not a new risk of enfranchisement. But it is a change in the economics of an existing risk.
The freeholder still has to deal with the claim, but will generally have to bear its own legal, valuation and other process costs. That is, in fact, a perfectly ordinary economic arrangement.
In most property transactions, each side pays the professional costs it incurs in conducting its own side of the transaction. The unusual feature of historic leasehold enfranchisement was that the freeholder could generally recover its reasonable process costs from the leaseholder. When commenced LAFRA will largely remove that advantage.
The litigation regime is also changing with the impending commencement of the relevant parts of LAFRA later this year/in early 2027. The existence of disputes and litigation is nothing new, but the allocation of costs is.
LAFRA provides greater protection for leaseholders against paying landlords’ litigation costs in relevant circumstances and gives leaseholders a route to seek recovery of their own litigation costs where a court or tribunal considers that appropriate.
Taken together, these changes alter the financial consequences of owning the freehold.
That is what matters for the risk premium. The comparison needs to be made again. The purpose of a risk premium is to capture the different risk associated with owning a freehold asset compared to a risk-free alternative (gilt).
The question for the Government is therefore, not whether the Sportelli premium was reasonable in 2007, but how this has evolved since then.
The freehold carries an income stream and a distant reversion, but it also carries liabilities and costs.
Since 2007, building-safety responsibilities have materially altered the potential liability of some freeholders, while the reforms to RTM, enfranchisement and lease-extension costs change the extent to which the freeholder can recover the costs of dealing with statutory rights. The litigation-cost regime is changing as well.
Those factors do not prove that the risk premium should be higher. They do prove that the question needs to be examined rather than assumed away.
And the answer should not be derived solely from theory. It should be tested against the transactions taking place in the real world.
If investors are buying ground-rent investments with an implied capitalisation rate of 9%, the Government needs to understand why a statutory valuation should assume a materially lower yield.
If freehold transactions with distant reversions imply a return different from the prescribed deferment rate, that evidence also needs to be understood. Perhaps there are good reasons for the difference. However, if the market and the statutory model produce different answers, Government should be able to explain the gap.
There is a danger that valuation practice becomes circular. A rate is established, valuers use it, tribunals become accustomed to it and, after enough years, its widespread use is treated as evidence that it must be correct.
But historical convention is not market evidence. The Government has the opportunity to break that cycle. The new statutory system should be based on rates that reflect the investment economics of the asset being valued today, not simply numbers inherited from a valuation regime established in 2007.
That does not mean abandoning Sportelli. It means testing its assumptions properly.
That, however, brings us to a more fundamental question. We have spent much of this analysis asking what the market rate is today, and there is good reason to do so.
If the Government says that the prescribed rates are intended to reflect market value, then actual investment evidence must be the starting point.
But it does not necessarily follow that it should also be the end point. The market tells us what return investors may require to own a freehold; it does not, by itself, tell us whether that is the outcome Parliament wants from a system which the Government is simultaneously trying to reform because it considers leasehold economically inefficient and unfair.
There is a difference between establishing the economics of the existing system and deciding what the reformed system should be designed to achieve.
There is also a rather obvious way for the Government to resolve that policy question.
Matthew Pennycook, the housing minister, himself proposed, during the passage of LAFRA, a short amendment requiring the Secretary of State, when setting the deferment rate, to have regard to “the desirability of encouraging leaseholders to acquire their freehold at the lowest possible cost”.
The amendment was rejected at the time, but the Government is now preparing the forthcoming Commonhold and Leasehold Reform Bill to make further amendments to the 2024 Act. It therefore has an opportunity to put that principle into the legislation after all.
That would make explicit something that risks being obscured by the technical language of valuation. Market evidence should establish the investment economics, and the Goverment Actuary’s Department work on yields, property-price growth and the risk premium should be rigorous enough to establish what those economics actually are.
But if ministers also believe that leasehold imposes a wider economic cost and that public policy should make it easier and cheaper for leaseholders to escape that system, Parliament can say so.
The prescribed rate would then be informed by both the evidence about the return required to own the freehold and the statutory objective of making enfranchisement cheaper.
That is a much more honest debate than pretending that the market rate is the only possible answer when the Government itself has decided that the tenure which produces that market is one it wants to dismantle.
Related posts:
 Why it is going to be so important to shout in 2025 – and loudly – when government sets the leasehold Deferment Rate
 Government’s proposed £250 ground rent cap has already busted the freehold market – and should make lease extensions cheaper right now
 Leasehold valuation rates: the government consultation where numbers matter more than slogans
 Even if government wins Judicial Review, half of all leaseholders could be left worse off by unfavourable deferment and capitalisation rates. (And conversion to commonhold would be toast, too)
 Leasehold and Freehold Reform Bill: the most important part of the enfranchisement bit is missing
 Government’s proposed £250 ground rent cap has already busted the freehold market – and should make lease extensions cheaper right now








Over the last ten years, there has been a great deal of discussion about reform, including proposals that have amounted to the near-confiscation of ground rents, such as those advocated by the likes of Gove. This has inevitably affected the perceived value of such income streams. You can hardly calculate an appropriate capitalisation rate from a market that has been so distorted by such wild and speculative proposals.
It is also important to bear in mind that the fundamental principle when valuing such interests is that the valuation is conducted in a “No Act World”—that is, assuming the relevant legislation and proposed reforms do not exist.
Stephen it’s also true to say the ground rent landlords have had 33 years of pushing up the rates to advantage themselves. All the graphs and all the court decisions work to their advantage. It can never be economically viable for a leaseholder to fight things up the court system. The leaseholder has no way to recover their costs, are only arguing for their own lease. Conversely GR investors are fighting to maximise their portfolio value that might include hundreds or thousands of leases.
A 15x GR multiple seems more than generous?
Is the “no act world” also intended to advantage the GR punter.
The only way to truly find the no act world is to look at the market before the Act, and try to imagine how that market would have changed in the absence of the Act. In my view – unevidenced – ground rent values were low pre 1993, and they rose partly due to interest rates and capital looking for investment opportunities, but as much if not more so due to the system being gamed by freeholders, inflating freehold values under the act (which then increased the market value of the same freeholds).
What enfranchisement prices should be is debateable. It may well be higher than current market values, but it is no-where near what they reached in peak freeholder “gaming the system” times
The valuation models were ultimately decided upon by Tribunal members who were impartial. Yes, potential buyers of freeholds are scarcer. My oiwn experience is that other than sales by deceased estates the freeholds have come onto the market for sale by auction have been for one reason or another problemmatic ones and to try to analyse out the true value without knowing the story in each case is nigh on impossible.
The valuation “models” were decided on by imperfect human beings who were hopefully trying to do their best to be impartial. Not only that, they were to a very large extent hamstrung by the evidence in front of them which was often compiled at massive expense by freeholders using surveyors who would not find it particularly easy to justify that they were perfectly unbiased when giving evidence.
Give some examples of what things make them problematic
spot on, I would add that where the management is condicted by the lessees by means of their own Residents Management Conpany there is less risk to the reversioner of the hassle of suing non payers, etc., therefore it would make sense for different rates to apply for calculating valuation depending on whether the lessor is burdened with the management or if the Residents have control of it typically with their own Committee and Managing Agents
spot on Stephen that is
Freeholders always want it every which way. Are you saying a freehold is only worth owning if the person with ultimate ownership of the asset is able to have all the benefits of ownership with none of the hassle or risk?
That’s hilarious Stephen, you’d make a great economist. Should we also include the extra insurance revenues and other fee income freeholders have engorged themselves on.
Stephen,
In a market econony, the value of all investments – both financial assests and tangible or intangible alternatives – is determined primarily by decentralised forces of supply and demand. The above article makes that abundantly clear to me, and reminds me that “something is worth what the buyer offers and the seller accepts”.
But there has always been the possibility of the unforeseen affecting the balance between freeholder and leaseholder leading to an intervention. An example is, of course, the Fire of London Disputes Act 1666 (18 & 19 Cha. 2. c. 7) which enacted an answer for a specific example. Arguably, climate change with flooding and subsidence, and building safety costs are similar new events. As is the government response in part reflecting pressure from developers and builders as well as leaseholders. The precedent is there even if some freeholders and tribunals ignored it and profited from doing so. If a brave new world of commonhold ensues, common and free holders will share the new uncertainties.
It’s been said before and sorry to repeat but this saga is a big ugly stain on every UK government and the civil service but particularly on the Labour government.
As for the message to investors , it’s simple – stop whining!
Seriously, do investors and freeholders expect to have the government i.e. the money from millions of taxpayers – they do know what tax is, right? – working in ordinary jobs for ordinary money, continue in perpetuity guaranteeing or underwriting gambles on ever-increasing property values – because what else is leasehold but a rigged property system established by some self-appointed ‘kings’ and their friends hundreds of years ago – and the barely-taxed portfolios of their investments by punishing leaseholders without the entire system crashing soon? Talk and delay is killing growth for homeowners, homebuyers and homesellers and the success of UK PLC is not dependant on retaining freehold for an over-protected minority, but on people wanting to move, live, work and remain in the UK. While investors calculate how this tweaking of a system will affect the return on their already considerable under-taxed asset wealth, that wealth is adding nothing to this economy and leaseholders are just trying to keep a roof over their heads and to remain in the homes for which they paid , unlike , for example, the ancestors of the aristocracy and crown and the CoE.. Is this a gangster state or a modern, progressive capitalist democracy? Remember that caveat about investments which can go up or down in genuine market economy? In terms of change and progress and updates to legislation, must the perfect always be the enemy of the good?
I’ve done some rough calcs on GRIO, the listed ground-rent investment fund.
GRIO is currently trading at 17p/share; with c.100M shares that’s £17m equity value. Current debt is c.£4m (let’s be conservative and assume nil cash), so Enterprise Value (EV) is £21m. With an annual ground rent roll of c.£4.9m; market-value EV is 4.3x annual ground rent (GR multiple).
GRIO’s own Net-Asset-Value (NAV) is 32p/share. NAV is what the fund says it is worth – so it is trading at almost a 50% discount to NAV – and in fact has done so for many years. Even at 32p/share; EV is £36m and 7.3x GR multiple.
So frankly, any freehold conversion at more than 4.2x GR multiple would represent unjust enrichment to GRIO shareholders.
And any freehold conversion at more than 7.2x GR multiple would represent more than the (umm..) conservative NAV the fund says it is worth.
PS.
The GRIO fund was always a one-way ticket to administration. Promoters should be sued and the zombie-industry it supports reallocated to more productive outcomes for the British economy.
Andrew,
I agree with you.
The financial drag caused by UK zombie companies is heavily choking economic growth by locking up capital , credit lines, and skilled workforce talent that otherwise flow into high – growth startup enterprises,
The phrase “capital misallocation” sums it all up to me and remains a primary driver behind the UK’s decade long sluggish productivity rates.
I am note sure the market is quit as dead as some think.
Lot 203 Holly House Brentwood (Allsops 18/09/2026) has a Ground Rent of £4,454 (per addendum) and 2 shorter lease flats (48 yrs remaining – currently valued in an auction at say £15k each) for £150,000 plus auction fees of £2,000 plus a contribution to the sellers sale costs (say another £2,000) and you get to a figure of £124,000 for the existing long leashold ground rents or a multiple of 28 times or a return of 3.6%.
(GIRO is interesting, but in its wind-up stage, the value now largely reflects the disproportionate management fees compared with the now very modest income.)
The £250 cap, which applies regardless of whether the leaseholder is proposing to enfranchise, represents an interference with the landlord’s right to income. Such interference can be justified under A1P1 if it is proportionate and in the public interest.
However, a meaningful percentage of flats are held as investments, and many flats have been bought after the original grant of the lease, when the terms were fully understood. Since around 2017, one of the first questions buyers ask is: “What is the ground rent?” This suggests that many purchasers fully understood the lease terms when entering into the contract.
Therefore with many understanding the terms of the lease they agreed to and with some 30% of flats held by investors the idea of capping a rent just to put a couple of pound a week into the pocket of such leaseholders would seem challenging – far more meaningful reform would be to allow the initial rent agreed to the starting point and all future rises the lower of inflation or what’s in the lease . Allow leaseholders to extend keeping the existing ground terms would really deliver meaningful savings gets rid of 10/15 year doublers and avoids any challenge on A1P1
Many investors therefore believe there will be some watering down of the proposals and, to quote Rothschild: “Buy when there is blood in the streets, even if it’s your own.”